Time SeriesQMLERobust Inference
ARMA/QMLE Under Weak Dependence
Studies inference for ARMA models when innovations may be weakly dependent rather than IID, with emphasis on robust covariance estimation and finite-sample inferential performance.
Research
My work spans statistical inference under dependence, predictive modeling and uncertainty, financial time series, and the evaluation of computational systems under realistic operating constraints.
Statistical Inference & Time Series
Studies inference for ARMA models when innovations may be weakly dependent rather than IID, with emphasis on robust covariance estimation and finite-sample inferential performance.
Compares statistical and machine-learning methods using expanding-window, one-step-ahead forecasts, separating price prediction from the more difficult problem of forecasting noisy returns.
Examines the long-run behavior and uncertainty of a Gaussian financial model with bond factors, with current work focused on stationary distributions of key log-scale state variables.
Prediction, Machine Learning & Uncertainty
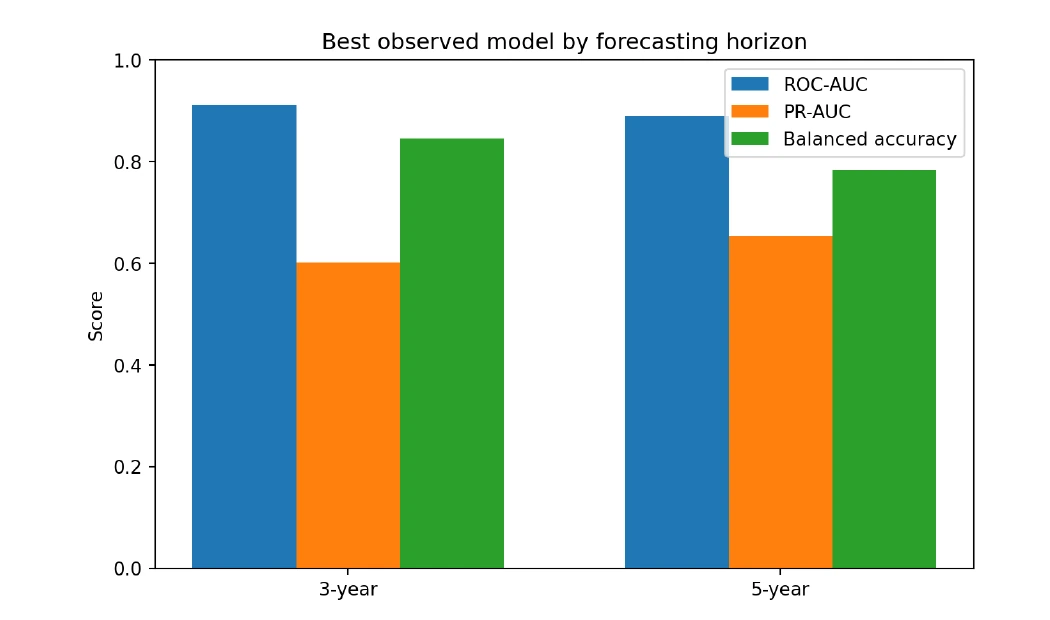
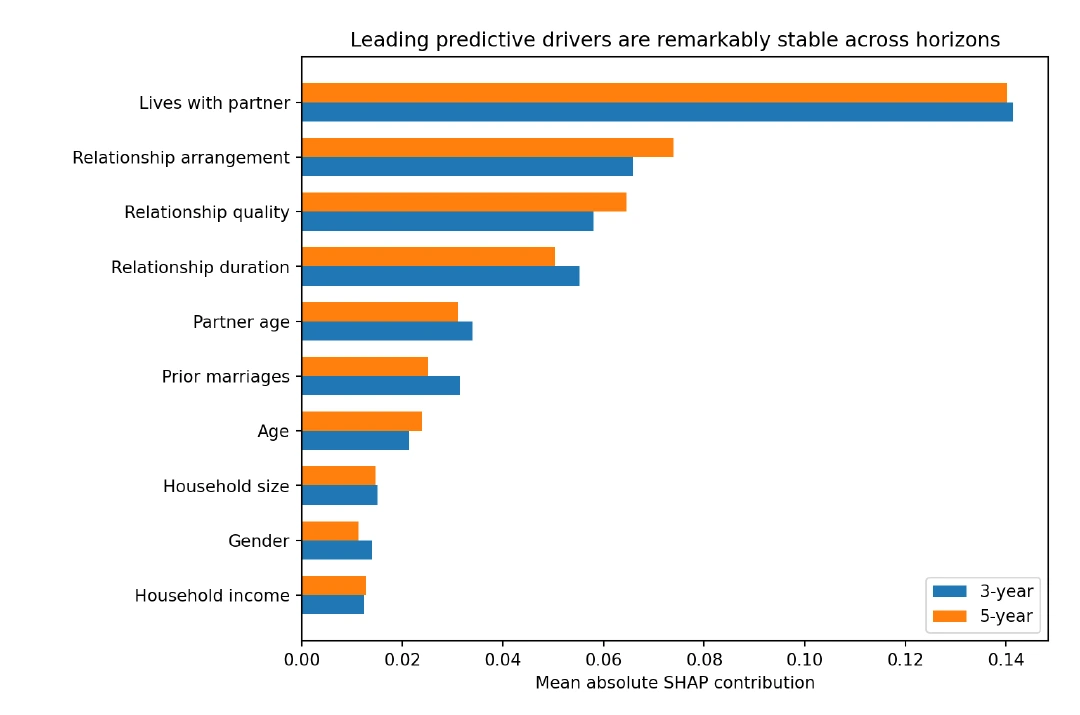
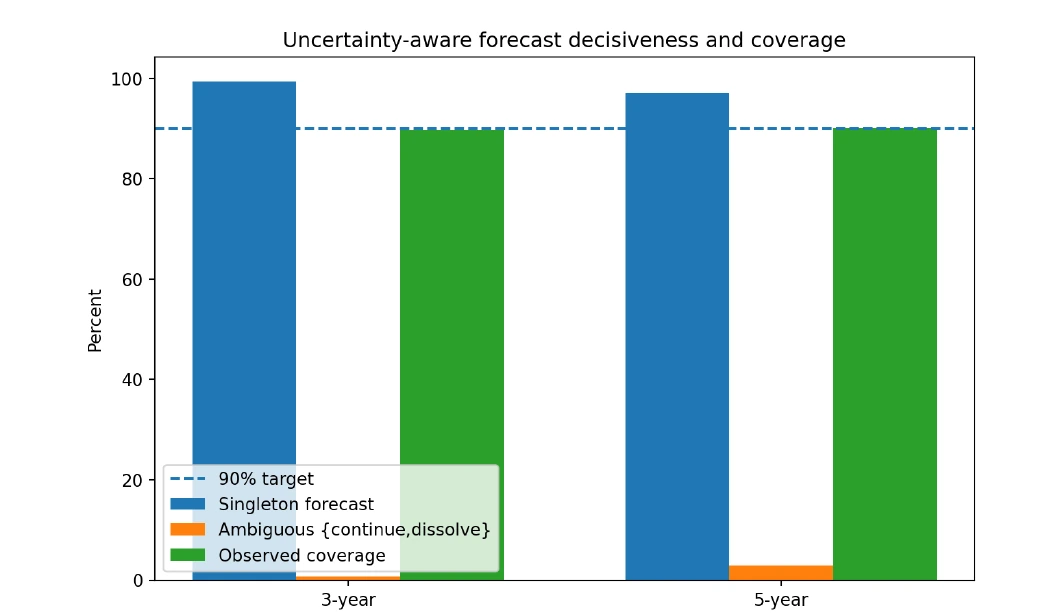
Uses longitudinal relationship data to examine how predictive performance, explanation stability, and uncertainty behave across three- and five-year forecast horizons. The emphasis is predictive rather than causal: whether conclusions remain reliable as the forecasting horizon changes.
Trustworthy Digital Systems
Develops and evaluates a server-authoritative attendance protocol using rotating session-bound QR credentials and uncertainty-aware geofencing, examining credential misuse and false-acceptance/false-rejection trade-offs.
Investigates how geolocation evidence and facial verification can be combined for in-person verification, comparing fusion strategies through false-acceptance and false-rejection behavior.
Earlier Research
Applied modeling work using intervention analysis, district-level data, and simulation to study malaria-control questions and support quantitative public-health decision making.